Home Insurance
Dwelling limits, deductibles, and the endorsements that decide what a claim actually pays. Crissy walks through the parts of a homeowners policy that only matter once you need them.
Explore home insurance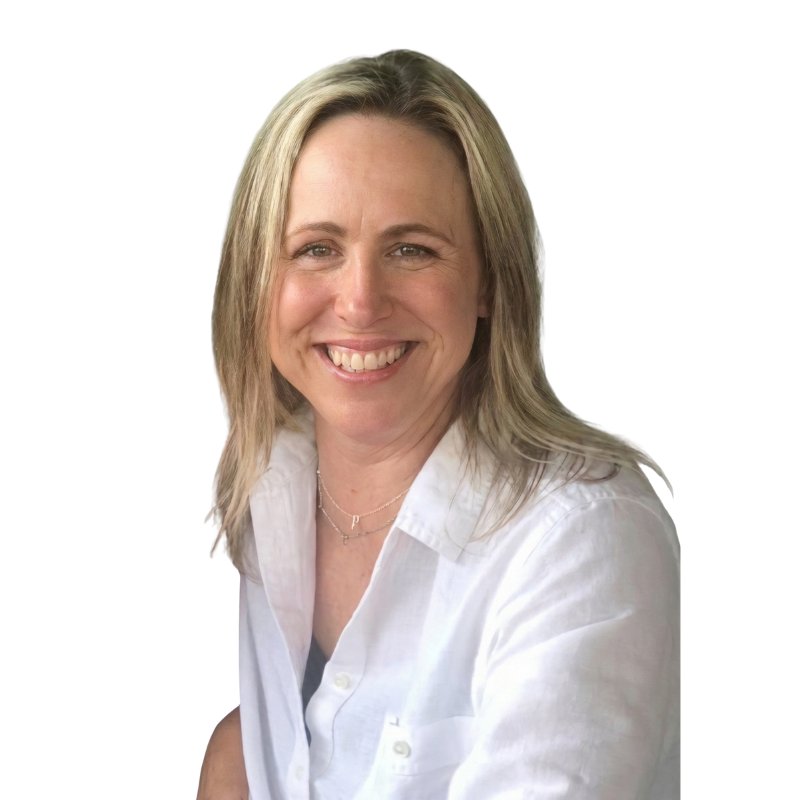
Most people meet an insurance policy twice: the day they buy it and the day something goes wrong. Crissy has spent over a decade on both ends of that — writing coverage and then handling what happens when it gets used.
Mon–Fri 8AM–5PM · Sat by appointment · After hours calls returned next business day
Crissy came into insurance through the side of the business most clients never see. Before managing the office, she spent years in claims support and policy administration — the work that happens after a loss is reported, when the wording of a policy stops being theoretical and starts determining what gets paid.
That history shapes how she writes coverage now. When she walks through a homeowners policy, she is thinking about the claim conversation that might follow in three years: whether the dwelling limit will still make sense, whether a deductible that looked attractive at signing will feel that way after a storm, whether a rider someone skipped is the one they will wish they had.
As office manager she also keeps the agency running day to day, which means she tends to be the person who knows where a file stands. Clients who prefer talking to someone who already has their history in front of them usually end up working with her.
Her background tends to draw a particular kind of question.
Clients who have filed a claim before and want to understand how it affects their coverage and rates
Anyone with a complicated policy history that needs untangling
Households wanting a plain-language walkthrough of what is and is not covered
Clients who want the same person handling their file year over year
Send the details below and Crissy will follow up, usually the same business day.
Calls after 5:00 PM will be returned the next business day.
Every line below is handled in the same Buford office, so your file does not get passed between strangers.
Dwelling limits, deductibles, and the endorsements that decide what a claim actually pays. Crissy walks through the parts of a homeowners policy that only matter once you need them.
Explore home insuranceLiability, collision, comprehensive, and the coverages people drop without realising what they were for. She will tell you which of your current limits she would question and why.
Explore auto insuranceTerm and permanent coverage for households who want a number based on their actual obligations — mortgage, income, dependents — rather than a figure that sounded about right.
Explore life insuranceHome and auto reviewed as one picture instead of two quotes. Bundling also means one renewal conversation and one person tracking both policies.
Explore bundling optionsBring your current declarations page from any carrier. Crissy reads it line by line and tells you what it covers, what it does not, and where the gaps sit. No charge, no obligation.
Schedule a reviewNo pressure at any stage, and nothing is in force until you say so.
Past claims, previous carriers, anything that has changed at the property or in the household. This is the part most quotes skip, and it is usually where the useful information lives.
You get a plain-language walkthrough of the limits, exclusions, and deductibles — including the ones that would matter in a claim rather than the ones that look good in a summary.
If you move forward, Crissy stays the point of contact at renewal and when something changes. Coverage begins only once a policy is issued and confirmed in writing.
Call during business hours for the fastest answer, or send the form and she will come back to you.
Work with buyers or borrowers who need coverage in place before closing? Send a referral to Crissy →